IT認証試験問題集
GOWUKAKU|IT認定資格の最新の試験問題集(PDF版・無料サンプル問題)を提供しています
 ホームページ / AICPA 問題集  / CPA-Auditing 問題集

AICPA CPA-Auditing 問題集 練習問題・模擬試験|日本語版&英語版対応

CPA Auditing and Attestation (CPA) 試験問題と答案

(0件のカスタマーレビュー)

最終更新日: 2026/10/23  収録内容確認済 | PDF問題集: 全 1,022 問収録

CPA-Auditing試験対策の学習資料(PDF版:日本語・英語2言語セット)|1年間(365日)無料アップデート付
CPA-Auditing 試験を開始する   
cpa-auditing_shiken_1
cpa-auditing_shiken_2

CPA-Auditing 問題集 仕様・サポート案内

対象試験 AICPA CPA-Auditing — CPA Auditing and Attestation (CPA)
収録問題数 全 1,022 問(解答付き/オンライン無料サンプル 120 問公開中)
提供形式・言語 PDF版(日本語版・英語版の2言語セット)
販売価格(税込) 6,880円(税込) ※1回払いの買い切り商品です。自動更新や追加請求はありません。
引き渡し・有効期間 決済完了後すぐにダウンロード可能(日本語版が準備中の科目は、英語版を即時ダウンロードのうえ、日本語版は準備完了次第ご登録メールへ自動送付・有効化されます)。ご購入日から1年間(365日間)無料アップデート対応(期間内の更新版も追加料金なしでダウンロード可能)。
お問い合わせ窓口 メールサポート:[email protected](注文確認・再送・教材に関するご質問|返金・交換条件)

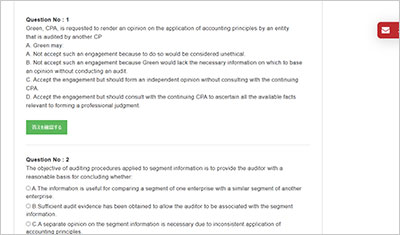
CPA-Auditing サンプル問題プレビュー(抜粋)

収録内容から抜粋したサンプル問題です。「解答・解説を表示」をクリックすると正解を確認できます。

サンプル問題 1: Several sources of GAAP consulted by an auditor are in conflict as to the application of an accounting principle. Which of the following should the auditor consider the most authoritative?

  • A: FASB Technical Bulletins.
  • B: AICPA Accounting Interpretations.
  • C: FASB Statements of Financial Accounting Concepts.
  • D: AICPA Technical Practice Aids.
正解:A
Explanation: Choice "a" is correct. In accordance with the GAAP hierarchy, FASB Technical Bulletins are considered the most authoritative of the sources listed in the question. Choice "b" is incorrect. Of the sources listed, AICPA Accounting Interpretations would be considered the second most authoritative. Choice "c" is incorrect. FASB Statements of Financial Accounting Concepts are among the least authoritative sources of GAAP available to auditors. Choice "d" is incorrect. AICPA Technical Practice Aids are among the least authoritative sources of GAAP available to auditors

サンプル問題 2: For an entity's financial statements to be presented fairly in conformity with generally accepted accounting principles, the principles selected should:

  • A: Be applied on a basis consistent with those followed in the prior year.
  • B: Be approved by the Auditing Standards Board or the appropriate industry subcommittee.
  • C: Reflect transactions in a manner that presents the financial statements within a range of acceptable limits.
  • D: Match the principles used by most other entities within the entity's particular industry.
正解:C
Explanation: Choice "c" is correct. Financial statements are presented fairly in conformity with GAAP when there are no material misstatements included therein. The fact that there may occasionally be immaterial misstatements means that the financial statements are correct "within a range of acceptable limits." Choice "a" is incorrect. Accounting principles may change from year to year. As long as such changes are properly accounted for, the financial statements are still in conformity with GAAP. Choice "b" is incorrect. The AICPA and the FASB determine GAAP, not the Auditing Standards Board. Choice “d" is incorrect. There is no requirement that an entity's financial statements be prepared in accordance with prevalent industry practices in order to be in conformity with GAAP.

サンプル問題 3: Which of the following statements is correct concerning an auditor's responsibilities regarding financial statements?

  • A: An auditor may not draft an entity's financial statements based on information from management's accounting system.
  • B: The adoption of sound accounting policies is an implicit part of an auditor's responsibilities.
  • C: An auditor's responsibilities for audited financial statements are confined to the expression of the auditor's opinion.
  • D: Making suggestions that are adopted about an entity's internal control environment impairs an auditor's independence.
正解:C
Explanation: Choice "c" is correct. An auditor's responsibility is to express an opinion on financial statements based on an audit. Choice "a" is incorrect. An auditor may draft an entity's financial statements based on information from management's financial system. This would be referred to as a compilation engagement. Choice “b" is incorrect. The adoption of sound accounting policies is an implicit part of management's responsibilities, not the auditor's responsibilities. Choice "d" is incorrect. An auditor often makes suggestions that are adopted about an entity's internal control environment. Professional Standards

AICPA CPA-Auditing試験の準備に向けた復習資料としてCPA-Auditing問題集を提供しています。CPA Auditing and Attestation (CPA)試験の主要な知識ポイントをカバーしています。ページ上部の「CPA-Auditing 試験を開始する」ボタンからオンライン無料サンプル問題を確認できます。

CPA-Auditing問題集の収録内容と更新状況はどうなっていますか?

答え:現在提供されているCPA-Auditing問題集には、CPA-Auditing試験対策に向けた全1,022問の練習問題と解答が収録されています。CPA Auditing and Attestation (CPA)試験に向けた復習に利用できます。

CPA-Auditing問題集はいつ更新されますか?

答え:最新の更新日時はページ上部に表示されています。出題範囲の改訂に合わせて、CPA-Auditing問題集は継続的に更新されています。更新では既存の基礎の上に新しい問題や改訂内容が反映されます。

CPA-Auditing問題集を覚えれば試験に合格できるのではないですか?

答え:問題と解答の選択肢をただ覚えるだけでは十分ではありません。基礎知識を学習したうえでCPA-Auditing問題集を練習することを推奨します。背景にある概念を理解しておくことで、応用問題にも対応しやすくなります。

CPA-Auditing問題集に解説は付いていますか?

答え:すべての問題集に練習問題と解答が収録されており、一部のAICPA科目の設問には解答の下に解説や補足説明が付記されています。理解を深めながら復習を進めるのに役立ちます。

試験の時もCPA-Auditing問題集のようにいくつかの答えを選ぶようにヒントを与えますか?

答え:選択問題では指定された数の選択肢を選びます。単に解答の記号を暗記するのではなく、問題文の意図と各選択肢の内容・解説を理解して学習を進めてください。

どうやってCPA-Auditing問題集を使って復習しますか?

答え:時間の許す限り、内容を理解しながら計画的に復習することをお勧めします。CPA-Auditing問題集の多くの設問と知識ポイントを一度の学習ですべて定着させるのは難しいため、3回に分けて反復する方法が効果的です。1回目は全体を通して解説とあわせて理解し、2回目は分野ごとに自分の言葉で説明できるか確認し、3回目は試験直前に間違えやすい設問を中心に総復習します。

学習時間が限られている場合は、CPA-Auditing問題集の選択問題を中心に重要キーワードと正答の根拠を優先して整理してください。また、ドラッグ&ドロップ問題やシミュレーション形式の設問については、手順や前提条件を含めて仕組みを理解しておくことが重要です。

アップデートおよび返金ポリシーについて

1年間の無料アップデート
ご購入日から1年間(365日間)は、CPA-Auditing問題集の更新版を追加料金なしでマイページからダウンロードいただけます。

返金ポリシー
返金の条件は返金ポリシーに従います。具体的なお手続きについては、ご注文情報をご用意のうえ、サポート窓口までご連絡ください。

コメントを残す

採点